A stock yielding more than any other component in the Dow Jones Industrial Average sounds like an income investor’s dream. For Nike, it is the arithmetic of collapse. Shares trade around $35.55, carrying a dividend yield of roughly 4.6%, a figure that looks generous until you ask what is actually backing it.
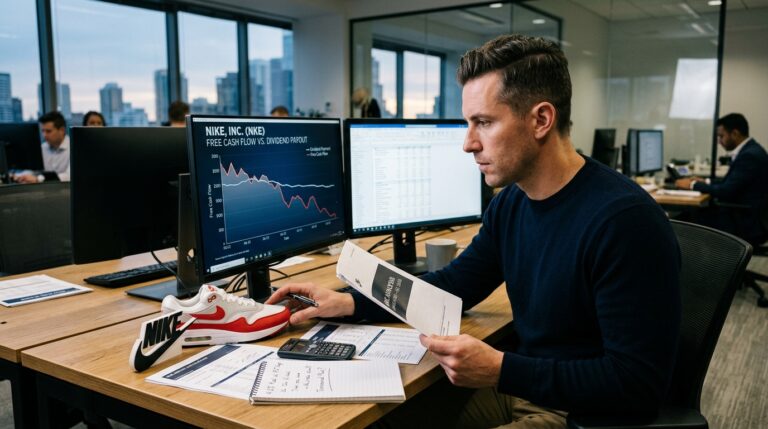
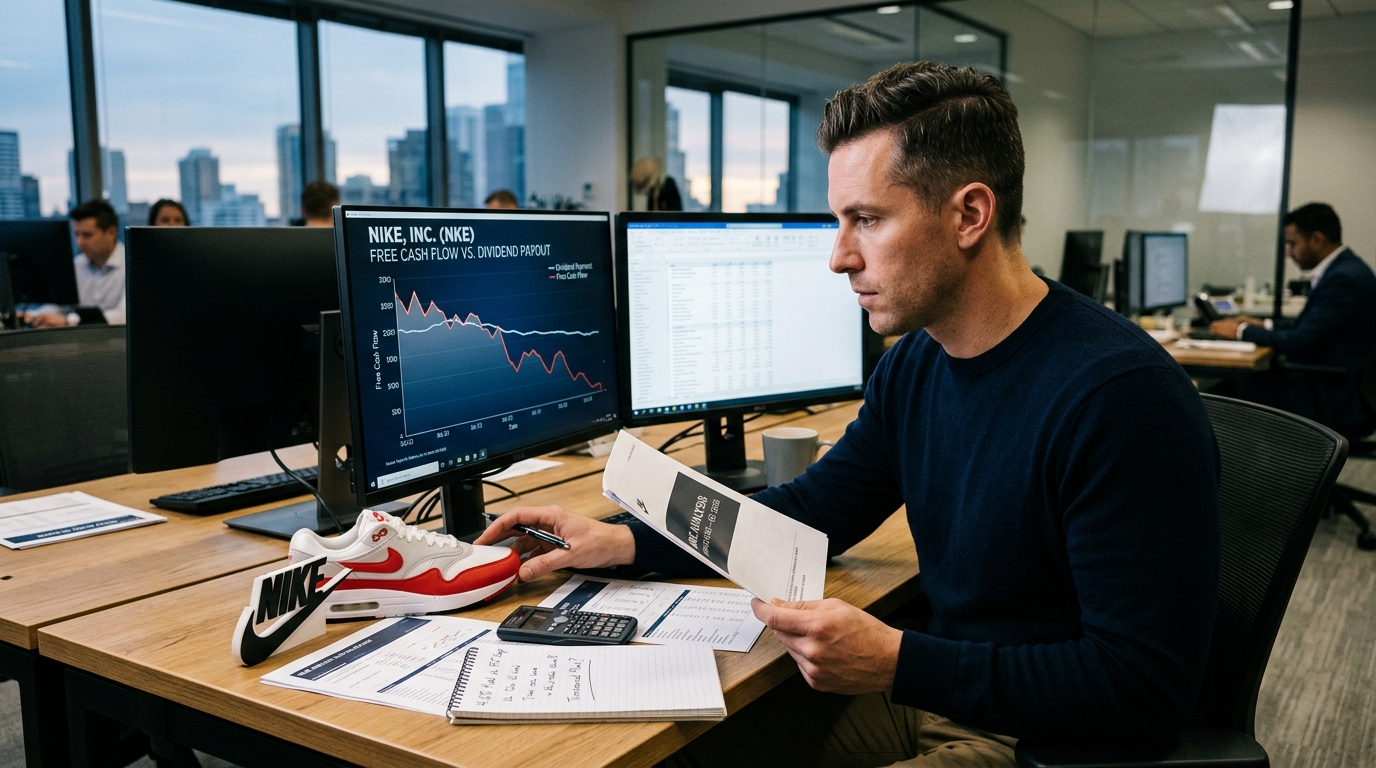
Nike generated approximately $2.18 billion in free cash flow in fiscal 2026 but paid out approximately $2.4 billion in dividends, meaning the company paid out more in dividends than it produced in free cash flow. That gap is the core of the investment question. Nike currently pays $0.41 per quarter, or $1.64 per share annually, putting the payout ratio at roughly 78% against fiscal 2026 diluted EPS of $2.10. On earnings alone the dividend looks manageable. On cash generation it does not.
Fiscal 2026 revenue was flat at $46.4 billion, net income fell 3% to $3.1 billion, and Nike Direct revenue dropped 6% while Converse revenue plunged 31%. That is the company CEO Elliott Hill inherited when he returned to lead the turnaround. Wholesale revenue did increase 6% and gross margin improved 20 basis points for the year, which are the numbers bulls cling to as early proof that the rebuild is working. The gap between those two data points, improving wholesale while direct crumbles, defines where the turnaround stands today.
The analyst community has grown sharply more skeptical. Morgan Stanley resumed coverage with an Underweight rating and a $31 price target, citing risks of negative EPS revisions, while BMO Capital initiated at Underperform with a $30 target, flagging slowing lifestyle demand and lower margins. UBS cut its price target by 13% to $42 and flagged that Q1 fiscal 2027 EPS could miss consensus by $0.05. That is a wide range of bearish calls landing within the same week, and each one places a target below the current price.
Nike is trading near twelve-year lows around $36, and S&P Dow Jones Indices confirmed the stock will be removed from the S&P 100 before trading opens September 21, ending an 18-year tenure in the index. Forced selling from index funds tracking the S&P 100 adds mechanical pressure on top of the fundamental concerns.
Then there is the competitive backdrop. Kylian Mbappé, one of soccer’s biggest names, left Nike to sign with On Holding, a defection that is partly symbolic and partly tangible. On is winning in performance running. Lululemon shares have dropped over 50% this year, confirming this is a category-wide reset, not just a Nike-specific story, though that framing offers little comfort to Nike shareholders.
Nike reports fiscal Q1 2027 results on October 1 after the market close. Consensus heading into the release sits at roughly $11.37 billion in revenue and $0.45 in EPS. The more important number will be guidance. Last quarter, Nike beat on both EPS and revenue, partly aided by a tariff refund tied to the IEEPA tariff recovery, yet the stock still fell because forward guidance for the first half of fiscal 2027 came in flattish and China weakness persisted. A repeat of that beat-and-fall would confirm the market is no longer trading on headline results.
Nike is projected to improve free cash flow from $2.18 billion in fiscal 2026 to about $3.0 billion in fiscal 2027, according to analyst projections, which is what the bull case rests on. If that cash flow recovery materializes, the dividend is covered and the 25-year streak of consecutive payout increases survives. Nike has raised its dividend for about 25 consecutive years. Breaking that streak would be a significant signal.
The bear case is simpler: revenue does not grow, China stays soft, the payout ratio stays stretched, and the stock drifts toward the targets Morgan Stanley and BMO have already posted. The bull case requires October 1 to deliver genuine top-line momentum, not another tariff-assisted EPS beat that the market reads through in an hour. At $35 and a 4.6% yield, Nike is priced for the turnaround to take considerably longer than management is guiding. Whether that pessimism is the opportunity or the warning depends entirely on what Hill says in eleven days.