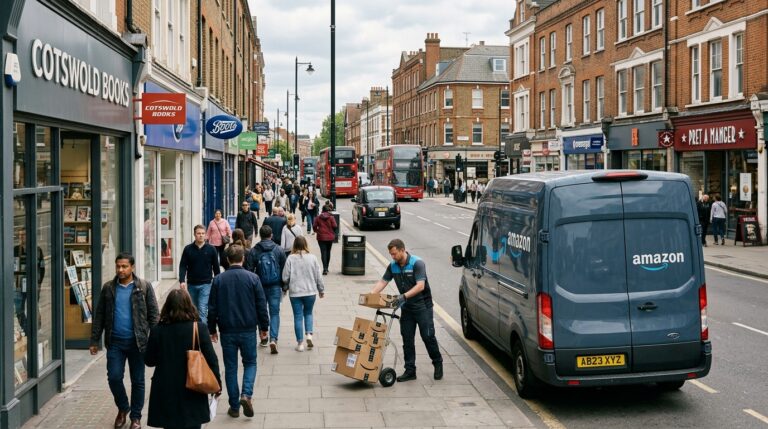
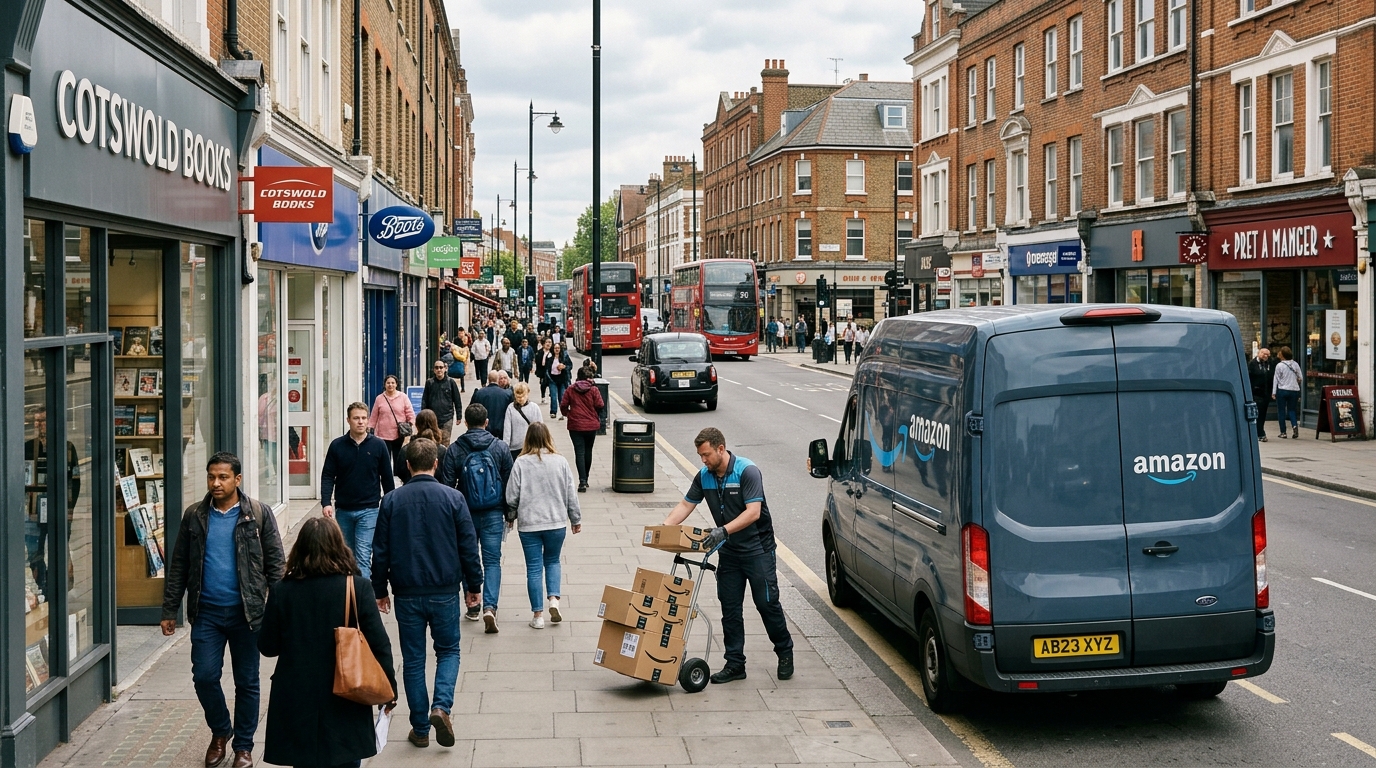
Two weeks before Chancellor John Healey delivers his first Budget on October 28, a single policy proposal reveals more about the government’s fiscal priorities than any pre-Budget speech. Healey is preparing plans to make major online marketplaces collect VAT directly from retailers selling goods on their sites, a measure that has been reported as a roughly £1bn-a-year revenue raiser. The proceeds would flow straight to high street shops in the form of lower business rates.
Online marketplaces would be responsible for collecting VAT when customers buy from business sellers whose annual turnover exceeds £90,000. The proposal builds on existing rules requiring marketplaces to account for VAT on certain sales facilitated by overseas sellers. What is new is extending that liability to UK-based sellers, closing a gap that has distorted competition for years.
The most striking detail is who supports it. Amazon has backed reform to extend VAT marketplace liability to UK-based sellers, and The Times reported Amazon estimated the change could raise around £700m for the Treasury, a figure below the government’s own projections but remarkable nonetheless. Amazon’s endorsement is not altruism. The company already collects VAT for its own first-party sales and competes directly against third-party sellers who have exploited weak enforcement. Levelling that playing field costs Amazon nothing and removes a competitive disadvantage.
MPs on the Public Accounts Committee have accused HMRC of failing to take the issue seriously enough, warning that sellers exploiting gaps in enforcement were undercutting British businesses. However, the committee’s widely cited £5.5bn figure refers to total UK tax evasion in 2022 to 2023, not losses from online marketplace VAT alone, and it is best read as a reminder of the scale of the enforcement challenge.
For investors watching UK retail, the direction matters as much as the sum. The Chancellor is reported to have ruled out a warehouse tax, and his move to target online sellers instead is likely to be warmly received by retail bosses, who have long argued that the high street bears a disproportionate tax burden compared to their e-commerce competitors. Companies like Next, Marks and Spencer, and B&M Retail stand to benefit most directly if a meaningful reduction in business rates follows. Marks and Spencer chief executive Stuart Machin has argued that retail accounts for 5% of the economy but pays more than a fifth of all business rates, describing the situation as unsustainable.
The broader Budget context makes this policy even more telling. British 30-year bond yields rose to a 28-year high last week as a global bond selloff pushed borrowing costs higher, adding pressure on Healey ahead of his first Budget. Yields on 30-year gilts peaked at 6.036%, their highest since January 1998. Estimates of how much this has eaten into the government’s fiscal headroom vary by source, but the direction is clear. A Treasury facing higher debt interest costs will look for every politically palatable revenue source it can find before October 28.
VAT compliance enforcement fits that description well. It raises real money, it targets behaviour that broad public opinion views as tax avoidance, and it simultaneously delivers a visible benefit to a sector that employs millions. Since the 2021 reforms that made online marketplaces liable for VAT on certain sales facilitated by overseas sellers, official and parliamentary evidence has pointed to an ongoing yield in the region of roughly £1.4bn to £1.8bn a year. Extending the model is the path of least resistance.
The wealth-building lesson here is not about Amazon’s share price. It is about reading government behaviour. When a Treasury is squeezed, it taxes the politically weak and rewards the politically vocal. Right now, UK high street retail is loud, organised, and sympathetic. The investors positioned in quality high street operators before that relief arrives may find they bought the catalyst at a discount.