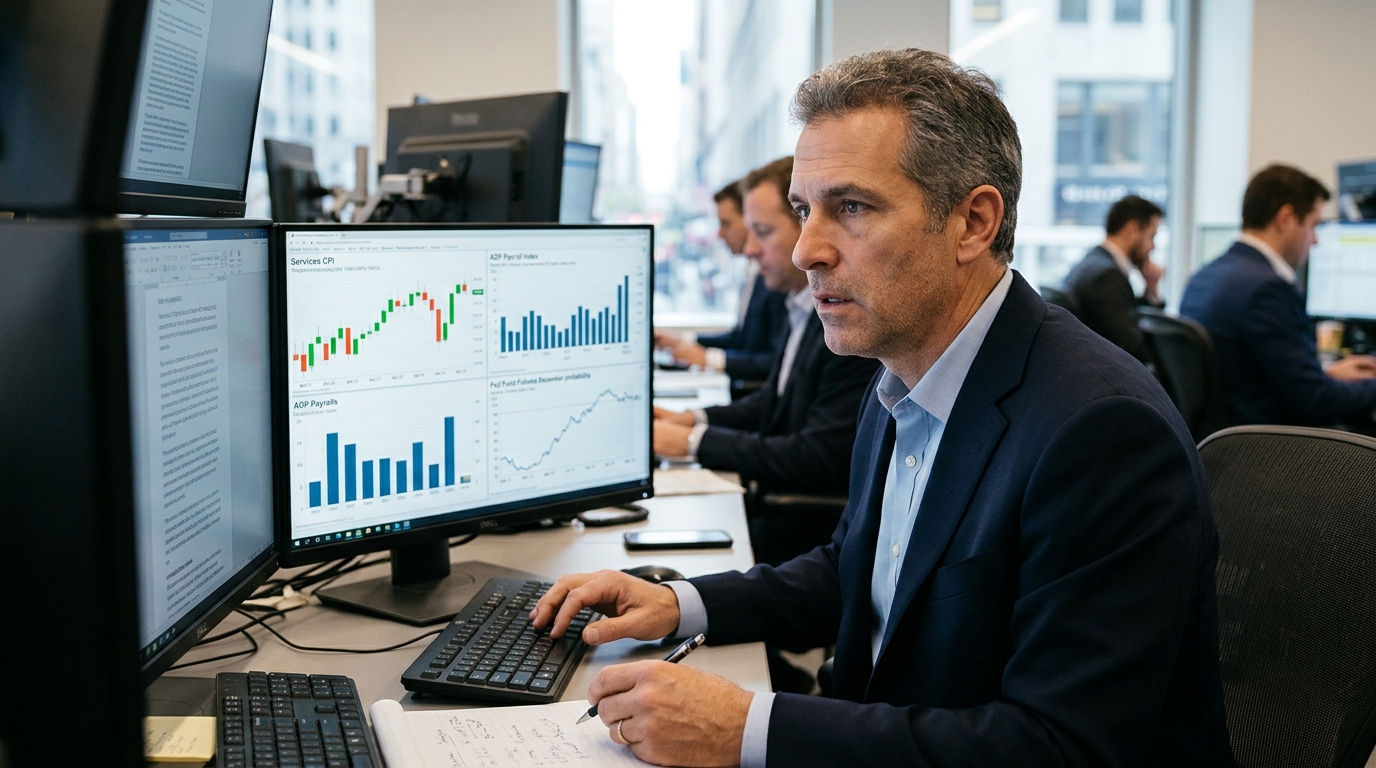
Two releases land this morning in a two-hour window, and together they carry more weight than almost anything left on the calendar before the December 9 Federal Open Market Committee decision. The ADP private payrolls count for October hits at 8:15 a.m. ET. The ISM services report for October follows at 10:00. By late morning, traders will have the last major services inflation datapoint the Fed sees before it votes.
The backdrop entering today is unambiguous. September’s ISM services prices paid index came in at 74.0, the highest reading since July 2022, while the headline PMI held at 54.9, well inside expansion territory. The employment subindex crawled back above 50 to 50.1, ending two consecutive months of contraction. Costs are rising faster than hiring. That combination sits uncomfortably close to the Fed’s core concern.
Then came Tuesday’s JOLTS. September job openings surged 333,000 to 7.523 million, and quits jumped to 3.365 million. By Tuesday afternoon, CME fed funds futures had priced a December 25-basis-point hike at roughly 85%, per CME’s FedWatch tool. The 2-year Treasury closed November 2 at 4.59%, up 112 basis points from the start of the year.
The Fed is currently holding at 3.75% to 4.00%. Two officials, Governor Lisa Cook and Cleveland Fed President Beth Hammack, dissented at October’s meeting in favor of an immediate hike. A December move would take the target range to 4.00% to 4.25%.
The Two-Way Risk
Scenario one: ADP beats 90K and ISM services prices stay above 73. December odds push higher. The 2-year yield extends its run, the dollar firms, and rate-sensitive sectors take the hit. Utilities are already down more than 6% from September and have underperformed the S&P 500 by roughly 13 percentage points year-to-date. A hot ISM print deepens that wound. Financials, which have gained about 9.5% over the trailing six months per Schwab sector data, hold their bid: net interest income expands if the Fed keeps tightening.
Scenario two: ADP prints soft and prices paid retreats meaningfully from 74.0. December hike odds compress from the high-70s back toward 60%. The 2-year yield pulls in. Rate-sensitive names, homebuilders, long-duration growth stocks, and utilities get a brief window to recover. The dollar weakens. Gold, which has tracked inversely to real rate expectations, bounces.
What to Watch at 8:15 and 10:00
Consensus for ADP sits near 67,000 to 69,000 October jobs, against 90,000 in September. A number north of 90,000 immediately reinforces the tight-labor read from JOLTS. A sub-50,000 print opens the question of whether September was an outlier.
For ISM services, the headline is secondary. The prices paid subindex is the number that moves the bond market. Watch whether it holds above 70 or breaks below that level for the first time since spring. The employment component matters too: if it slips back under 50 after one month above, that removes one piece of the Fed’s comfort on demand.
Trader’s Action Plan
Know your positioning before 8:15. The 2-year yield is the clearest real-time signal: a move above 4.65% after ADP signals the bond market is repricing December higher. A drop below 4.50% on a soft double-miss is a tactical entry window in rate-sensitive sectors.
Financials warrant attention on the long side into a hot outcome. Utilities and REITs deserve caution until the 10:00 ISM prices number clears. Friday’s October payrolls report is the final input before December, so size accordingly: today’s prints set the range, but Friday closes the argument.