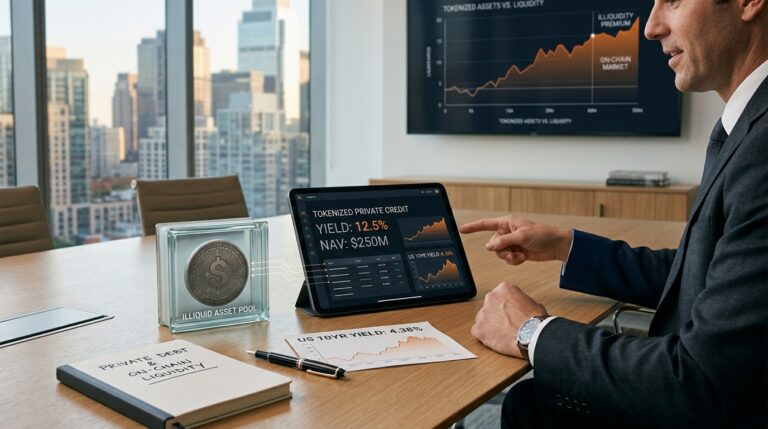
The number that is driving institutional interest in tokenized private markets is not a blockchain metric. It is a yield number. Yields in tokenized private credit are often marketed in the high single digits to mid-teens, reflecting the credit risk and the fact that most underlying loans are still illiquid relative to government debt. Against a 10-year Treasury below 4.5%, that spread is hard to ignore, and institutional allocators are not ignoring it.
Tokenized private credit is growing, but the headline numbers in circulation can mix different definitions and timeframes. Data providers that track on-chain private credit have put the category around the high teens of billions at times, but more recent snapshots have been notably lower. The trajectory matters as much as the size. Separately, the broader tokenized real-world asset (RWA) market was reported as expanding from about $8.8 billion on April 16, 2025, to roughly $29.9 billion on April 16, 2026, more than tripling in one year.
What is actually pulling institutional capital is not yield alone. It is a structural argument about redemption architecture. The traditional private credit model carries a design flaw that Blackstone’s BCRED made visible in 2026. BCRED’s tension point was a familiar liquidity mismatch: periodic repurchase offers sitting on top of multi-year, hard-to-sell loans, with the fund able to prorate requests when demand exceeds its stated quarterly limit. That mismatch is not a bug Blackstone failed to fix; it is inherent to the product shape. Tokenization offers a different answer. Tokenized private credit does not fix the underlying illiquidity of the loans. What it can do is make ownership and transfers more transparent and let allocators trade exposure through secondary venues that can run continuously, even if actual depth is uneven.
The Collateral Angle Nobody Is Pricing
The more original development is what managers are doing with tokenized fund shares beyond holding them for yield. Under a recent arrangement with Bybit, eligible clients can pledge Franklin Templeton’s tokenized money market fund shares to obtain USDT or USDC trading credit while continuing to earn yield on the underlying assets. The Bybit rollout follows similar arrangements with Binance and OKX, giving Franklin Templeton’s tokenized funds access across three major crypto trading platforms. That is a qualitatively new behavior: regulated fund shares operating as productive collateral inside crypto market structure, without liquidating the position.
In March 2026, the Federal Reserve, OCC, and FDIC jointly issued FAQs clarifying that an eligible tokenized security should generally receive the same regulatory capital treatment as its non-tokenized form. That guidance reduced a key uncertainty for banking organizations contemplating on-chain exposure.
Where the Thesis Gets Tested
The skeptics at Paris Blockchain Week made a point worth taking seriously. Industry speakers said tokenization can broaden access and issuance, but it does not by itself create active secondary markets for illiquid assets. Tokenization does not automatically make hard-to-trade assets liquid.
The concentration data reinforces the concern. Some market commentary has claimed that a small number of assets dominate tokenized market value, with the top handful accounting for a large share. The broader point is directionally right, but the specific figures vary by dataset and methodology, so investors should treat any single concentration statistic as illustrative rather than definitive.
The investment conclusion is therefore narrower than the headline growth figures suggest. Tokenized private credit is a genuine structural development, not a marketing cycle. But the yield premium is compensation for real credit risk and real illiquidity, regardless of what blockchain the loan lives on. The traditional private credit market has been estimated at roughly $3–3.5 trillion globally by industry groups. Even at on-chain volumes measured in the billions or tens of billions, this is a fraction of what institutional demand could eventually absorb. The infrastructure is being built by institutions with long time horizons. The secondary market liquidity to match the yield promise has not caught up yet.