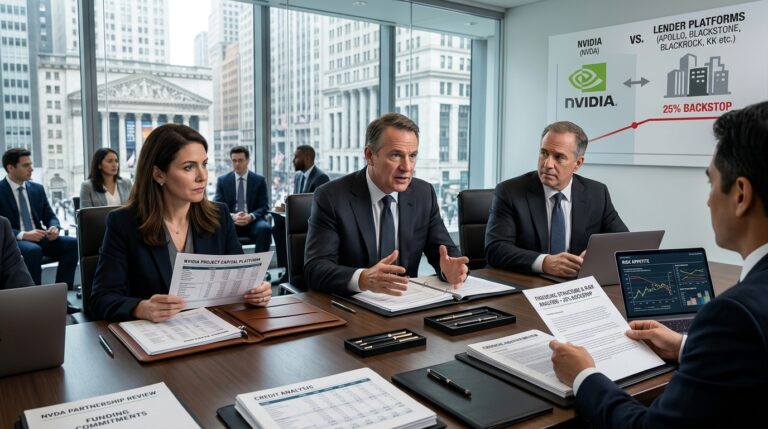
The Wall Street Journal reported this week that none of the $500 billion Nvidia announced in August has yet been deployed in a completed financing. The August partnership with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR was announced as a set of platforms designed to mobilize capital over time, not a single committed fund that those firms were required to fill.
The standard read on this story is that it is an administrative disappointment: a headline number that always outran the documentation. That framing is too comfortable. The more important signal sits inside the reason talks stalled.
The Guarantee Gap
The core contention between Wall Street and Nvidia has been how much Nvidia is willing to backstop the clients it wants lenders to support. Jensen Huang said in August that Nvidia’s credit support would top out at 25% of a project’s cost.
By contrast, Broadcom has disclosed a structure in which its backstop is keyed to 85% of outstanding amounts owed on a lease backstop, net of recovered asset value in a default scenario. Broadcom has also announced a $63 billion financing structure involving financial partners to enable AI compute capacity in partnership with Broadcom.
That gap is not a negotiating position. It is a structural argument about what GPU hardware is worth as collateral after the warranty expires. Residual-value support carries a correlation problem the 25% cap does not solve: a backstop written on Nvidia’s own chips pays out in exactly the quarter Nvidia’s revenue line is contracting, which is why lenders can treat it as weaker support than contracted lease payments from an investment-grade hyperscaler.
Broadcom can offer higher coverage because the obligation on the other side of its deal is a lease structure with contracted payments, rather than a bet that last cycle’s accelerators clear at a friendly price. Nvidia’s customers at the margin are smaller cloud operators whose credit quality lenders increasingly distrust.
What the Stock Market Has Not Priced
Equity investors have been told repeatedly that Nvidia’s financing initiative would extend the AI capex cycle by pulling more customers into the market. The logic was sound: vendor financing lowers the upfront cost of GPU clusters and smooths the revenue backlog.
None of that changes the lender calculus. The backstop is a residual-value guarantee: Nvidia would cover a shortfall if the chips lose value, and the two sides disagree on how long chips keep their worth. That disagreement is live and unresolved. The firms with the most experience pricing long-duration asset collateral have looked at the curves and declined to lend against them at the coverage level Nvidia proposed.
The leadership shift compounds it. Investor doubt is growing about whether the program will pan out, particularly given the cautious approach of interim CEO Colette Kress, who said on Tuesday’s earnings call: “We are rigorously evaluating future investments, commitments and guarantees.”
Stocks to Watch
Nvidia (NVDA) reported quarterly revenue of $115.8 billion and beat on earnings, but shares fell about 2.9% on Wednesday, reversing an initial post-earnings bounce. The financing impasse adds a demand-ceiling question on top of the leadership discount already in the stock.
Broadcom (AVGO) is the clearest beneficiary of Nvidia’s guarantee gap. Its willingness to backstop a structure tied to 85% of outstanding amounts owed under its lease backstop has made it a preferred partner for well-capitalized AI borrowers. That precedent gives Broadcom a durable structural advantage in vendor financing that equity markets have not fully recognized.
CoreWeave (CRWV) and Iris Energy (IREN) sit directly in the crossfire. CoreWeave’s senior unsecured bonds have traded at distressed-level yields, with market reporting recently placing parts of its unsecured curve above 16%, and the company relies heavily on debt markets to finance the data center capacity needed to fulfill signed contracts. CoreWeave’s structure depends on newer GPUs holding collateral value. If lenders at the $500 billion platform level are skeptical of that value, CoreWeave’s next refinancing faces the same friction, only without the Nvidia backstop to negotiate against.
The Apollo, Blackstone, and BlackRock refusal to fund on a 25% guarantee is not a procedural delay. It is the credit market’s verdict on what AI infrastructure collateral is worth when the chip vendor itself won’t stand behind more than a quarter of it. That verdict is already visible in stressed neocloud borrowing costs. It has not yet reached Nvidia’s equity multiple.