The debate about which industries AI will eventually disrupt has been answered by the data accumulating in 2026. The disruption is no longer theoretical, and the speed at which it is moving through specific sectors creates real positioning consequences for traders tracking capital flows and earnings revisions.
Where the Numbers Are Already Moving
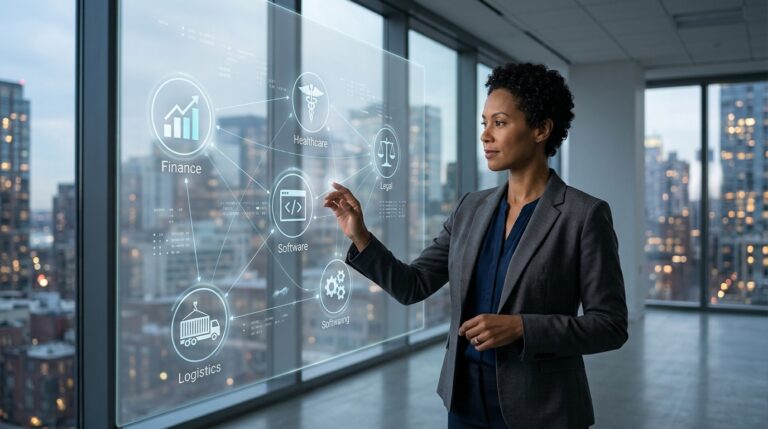
Financial services carries one of the highest confirmed displacement risks among white-collar sectors. The most concrete estimates are now coming from industry surveys and bank-specific headcount plans rather than generalized “job risk” scores. As of September 2026, the Institute of International Finance and EY reported that roughly 70% of institutions say agentic AI is moving from development into production, and about one in five expects agentic payment use cases in production within 12 months. Bloomberg Intelligence has estimated that global banks could cut as many as 200,000 jobs over the next three to five years as AI encroaches on tasks currently done by humans. PwC has also reported that productivity growth has nearly quadrupled in industries most exposed to AI since 2022, a set that includes financial services. That arithmetic does not resolve in favor of headcount.
Legal services are bifurcating sharply between the support layer and senior counsel. The highest near-term substitution pressure sits in document-heavy, repeatable work, while senior judgment and client stewardship remain less compressible. Harvey, the legal AI platform, announced a $550 million raise at a $15.5 billion valuation in September 2026 and said many of the largest U.S. law firms use it. Firms that delay AI-assisted review are losing business to faster, cheaper competitors running the same workflows at a fraction of the cost.
Healthcare: Administration First, Diagnostics Close Behind
U.S. healthcare remains heavily weighted toward administration, but the draft’s “approaching 1:1” staffing ratio is not a clean, widely standardized national benchmark and is too specific to leave standing. What is measurable is the regulatory pipeline for AI-enabled devices. As of September 2026, the FDA says it has authorized over 1,600 AI-enabled medical devices for marketing in the United States. Radiology still dominates this category: a peer-reviewed review of FDA-authorized AI and machine learning devices through June 2024 found that about 76% were radiology devices. On the clinical side, the acceleration is real, but the draft’s claim about “24” clearances in March 2026 could not be verified consistently across primary FDA reporting, so it has been removed. The near-term trade pressure remains on administrative cost lines and workflow vendors tied to billing, coding, imaging, and utilization management, where AI adoption is already operational rather than experimental.
Software and Logistics: The Unexpected Casualties
Software engineering was supposed to be safe. It is not. The Information reported that a Microsoft vice president told an engineering group to use an internal AI assistant to generate about half the code they write, and that layoffs later hit that team during broader cuts. Entry-level developer roles are under particular pressure because much of the work mix is code generation, documentation, and bug fixing. Google’s CEO has also said that about 75% of new code at Google is now generated by AI and then reviewed by engineers, up from about 50% by late 2025.
In logistics, the direction of travel is clear, but the draft’s specific dollar figures for the warehouse robot market and route-optimization savings were not supported by consistent, high-quality primary sources and varied widely by definition. A defensible anchor is that third-party market research firms generally place the global warehouse robotics market in the high single-digit billions for 2026, and that route optimization is one of the earliest AI use cases to show measurable cost reductions at the fleet level, mainly through fewer miles, lower fuel burn, and higher asset utilization.
The Trade Implications
This is not a uniform selloff in labor-intensive sectors or a simple long-AI, short-services thesis. Prior automation waves disproportionately displaced routine physical and clerical tasks. AI is disproportionately capable of performing cognitive and language-based work, which is white-collar territory. The winning trade is in the platforms extracting rent from that productivity shift: AI legal tools commanding $15 billion-plus valuations, financial AI vendors compressing headcount at the largest banks, and diagnostic AI clearing FDA authorization at an accelerating pace. The losing side of the trade is any company paying legacy labor costs in tasks that have measurable AI substitutes, without a credible plan to redeploy that margin.
Preparation means tracking the earnings calls where management begins describing productivity gains without corresponding revenue growth. That combination signals margin expansion from AI adoption, which is the real signal, not the press release announcing a pilot program.